
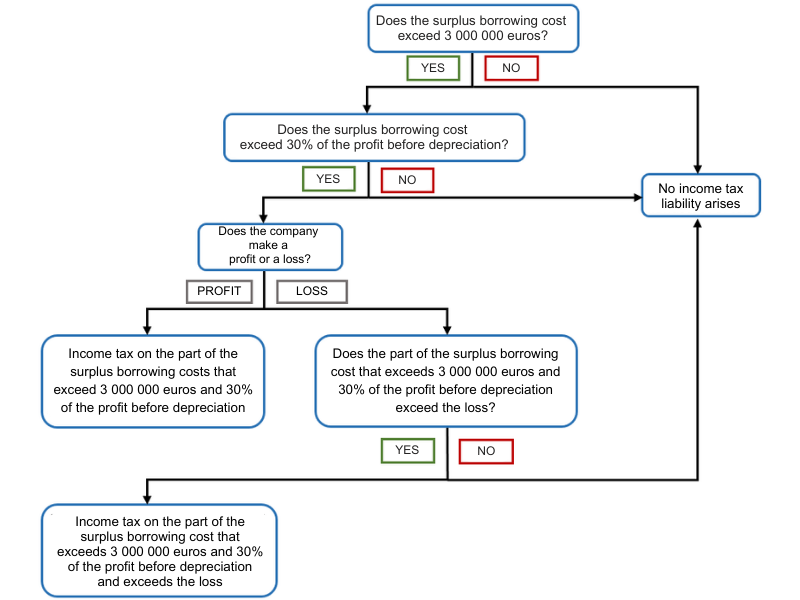
Below, we explain the measures against profit tax evasion set out in the Income Tax Act and result from Council Directive (EU) 2016/1164 (Anti-Tax Avoidance Directive, ATAD) and Council Directive (EU) 2017/952 (ATAD2).
Handbook “Specifications upon taxation with income tax”
""
1
|
1
Taxation of the surplus borrowing cost
Last updated on 08.01.2025
Last updated: 13.11.2025