
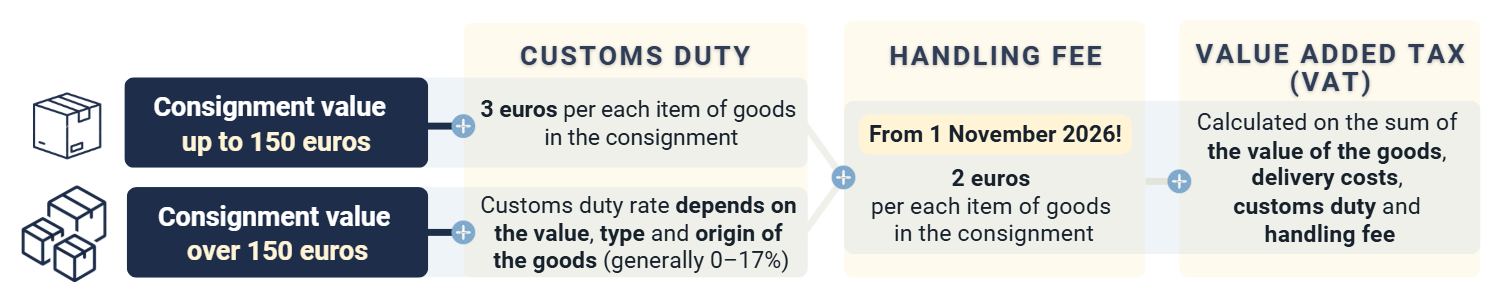
- The handling fee applies to goods ordered from online stores and sales platforms in non-EU countries and shipped directly to consumers.
- The purpose of the handling fee is to cover the costs associated with customs control and customs supervision of e-commerce consignments, which have grown rapidly.
- The handling fee is applied on a uniform basis across all EU Member States.
- The handling fee of 2 euros does not apply to gifts, i.e. parcels sent from one private person to another.
- If a customs declaration is invalidated, the customs handling fee will not be refunded.
The handling fee is imposed on the basis of Commission Delegated Regulation (EU) 2026/2152.
The change is part of the European Union’s customs reform, which aims to improve the control of rapidly growing e-commerce trade flows and help ensure that goods imported into the European Union comply with EU requirements.
Customs duty
From 1 July 2026, low-value consignments (valued at up to 150 euros) are subject to a customs duty of 3 euros per each item of goods in a consignment.
- The customs duty applies to goods ordered from online stores and sales platforms in non-EU countries and shipped directly to consumers.
The 3-euro customs duty does not apply to:
- consignments valued at over 150 euros, for which the customs duty rate (generally ranging from 0% to 17%) continue to depend on the value, type, and origin of the goods;
- parcels sent from one natural person to another, i.e. gifts.
Examples of calculating customs duty

There are three items in a parcel:
a T-shirt, a pair of jeans and a skirt.
Since the items have different commodity codes, each item must be declared on a separate line.
A customs duty of 3 euros must be paid for each item. Therefore, the total customs duty is 9 euros.

There are two T-shirts in a parcel, which have the same commodity code.
If the goods are declared as two distinct goods items (on two lines),
6 euros in customs duty must be paid.

There are two T-shirts in a parcel, which have the same commodity code.
If the goods are declared as a single goods item (on a single line),
3 euros in customs duty must be paid.
Declaration of goods and payment of taxes
The payment of taxes (including customs duty and handling fee) depends on which online shop or platform the goods were purchased from, who handles customs clearance, and whether the online shop or platform uses the Import One Stop Shop (IOSS) scheme for distance sales.
As a rule, private persons do not have to declare the consignment if they order goods from an online store or sales platform that has registered for the IOSS scheme.
In this case, the taxes are usually already included in the order price, and the customer pays them at the time of purchase. The declaration is submitted by the seller or their representative, using the IOSS scheme. In such cases, the consignee (a private person) cannot act as the declarant or submit a customs declaration in their own name using the seller’s or online store’s IOSS number.
However, if the recipient of the goods is asked to declare an IOSS consignment, we recommend that they first contact the seller, the sales platform or their representative (a postal or courier service provider).
Legal basis
Commission Delegated Regulation (EU) 2015/2446, Article 143a
amended with Commission Delegated Regulation (EU) 2026/1022
In exceptional cases, such as when an online store or sales platform outside the European Union is not registered under the IOSS scheme, the goods purchased for a fee are sent by a natural person, or similar, the recipient must submit the declaration independently, and pay the taxes, or use a representative (e.g. a postal or courier service provider).
The introduction of a customs duty of 3 euros on low-value consignments is one of the measures under the European Union’s (EU) customs reform, which aims to protect the EU internal market, prevent dangerous and non-compliant goods from entering the EU, make customs duty collection more efficient, and simplify controls so that they do not place an excessive burden on authorities or businesses. The change will apply in all European Union Member States.
As a further measure to regulate e-commerce, a handling fee for distance-selling consignments will be introduced from 1 November 2026, in addition to customs duty. The purpose of the handling fee is to improve the control of rapidly growing e-commerce trade flows and to help ensure that goods imported into the European Union comply with EU requirements. The handling fee will help to partially cover the costs associated with the customs control of e-commerce consignments.
Last updated: 26.10.2026

